Professional fund managers are supposed to be experts.
They have teams of analysts. Advanced algorithms. Years of experience. Fancy offices in London.
They charge you 1-2% per year for their expertise.
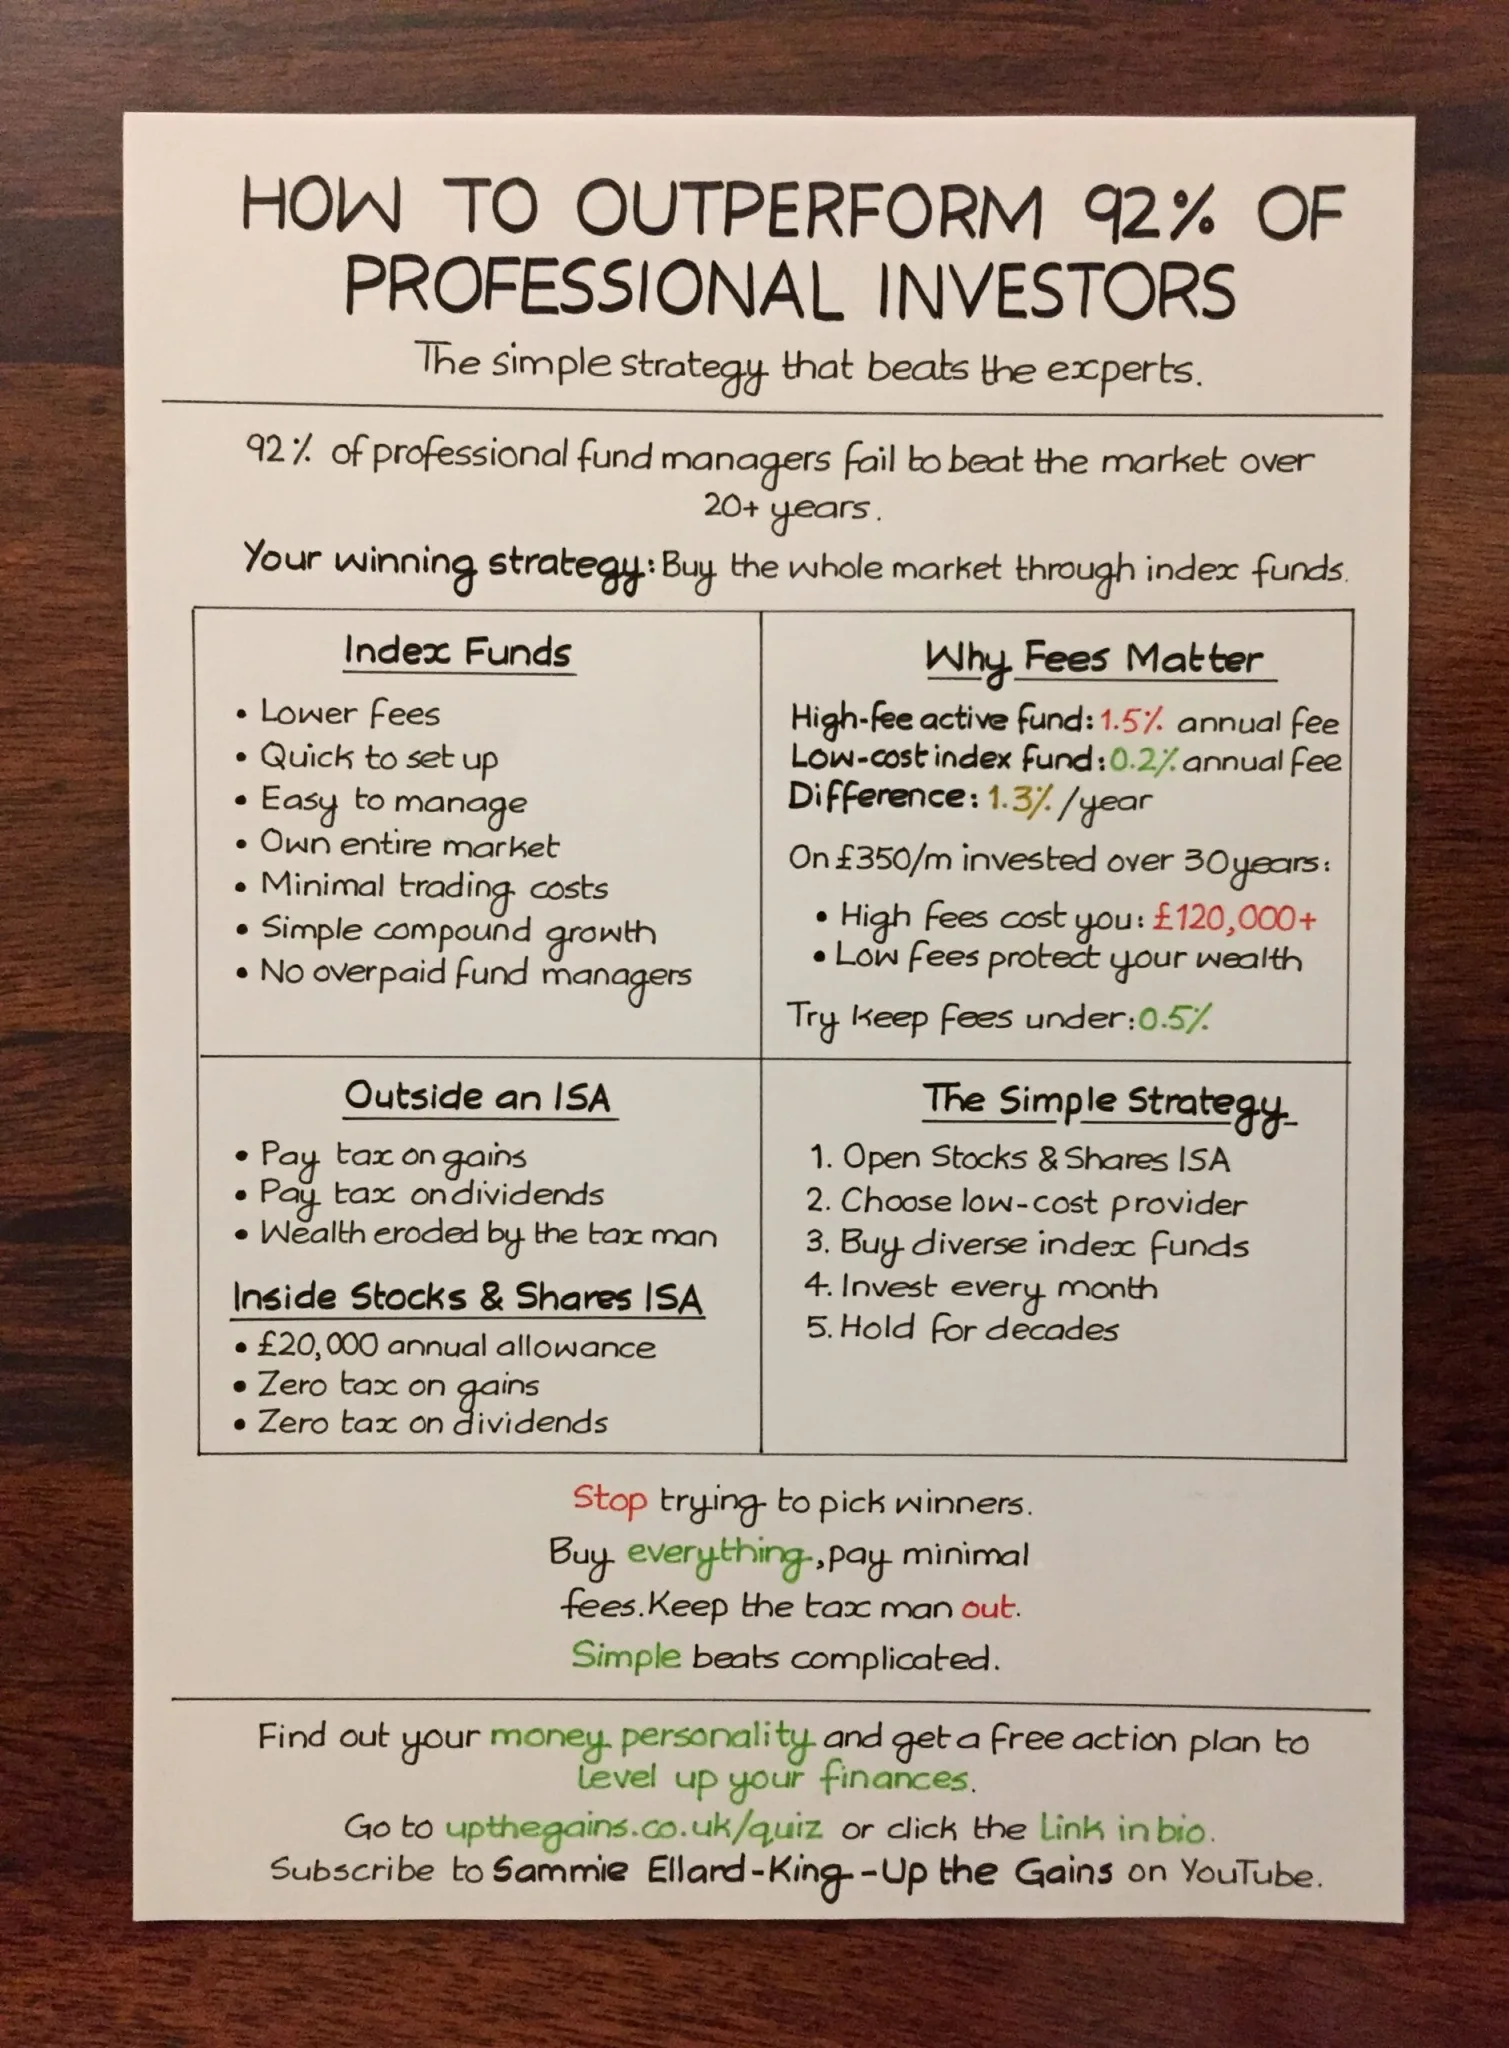
And S&P’s SPIVA research found around 92% of US large-company funds failed to beat the S&P 500 over 20 years.
Let me show you the dead simple strategy that beats nearly all of them.
The Uncomfortable Truth About Professional Investors
Over any given year, some fund managers beat the market.
They get profiled in newspapers, win awards and attract billions in investments.
But track them over 20+ years?
92% underperform a simple index fund.
Not because they’re incompetent.
Because beating the market consistently is nearly impossible. Even for professionals.
Why They Fail
Fees eat returns. They charge 1-2% annually. That’s a massive headwind. They need to beat market by 1-2% just to cover the fees.
Trading costs. Every time they buy and sell, they pay costs. Spreads, commissions, market impact. Adds up to another 0.5-1% drag on returns.
Overconfidence. They think they’re smarter than the market. They’re not. Nobody is.
Career risk. Fund managers can’t just own everything. They need to look active. So they make trades that hurt performance.
Timing is impossible. They try to predict which sectors will perform. They can’t. Nobody can consistently.
The professionals lose because the system is stacked against them. High fees. High costs. Forced activity.
You can avoid all of that.
Best ISA
Trading 212
Commission-free shares and ETFs in an ISA, Invest account or SIPP
Offer: Free fractional shares worth up to £100 with promo code GAINS (code must be used within 10 days of registering; value is random, most awards £8 to £25). Capital at risk, T&Cs apply.
- Commission-free trading, no account fee
- Pays interest on uninvested cash
- Stocks ISA and SIPP in one app
- CFDs in the same app: 77% of retail accounts lose money
- 0.15% FX fee each way on non-GBP trades
- Card deposits cost 0.7% after your first £2,000
- No Junior ISA or Lifetime ISA
- £1
- minimum
- Free
- platform fee
- Free
- trading fee
- 0.15% FX fee on non-GBP trades
Affiliate link. Capital at risk.
New to investing?
Get my free Checklist: the steps I would follow to open and fill an ISA without the classic mistakes. Plus one email a week, unsubscribe any time.
The Strategy: Buy The Whole Market
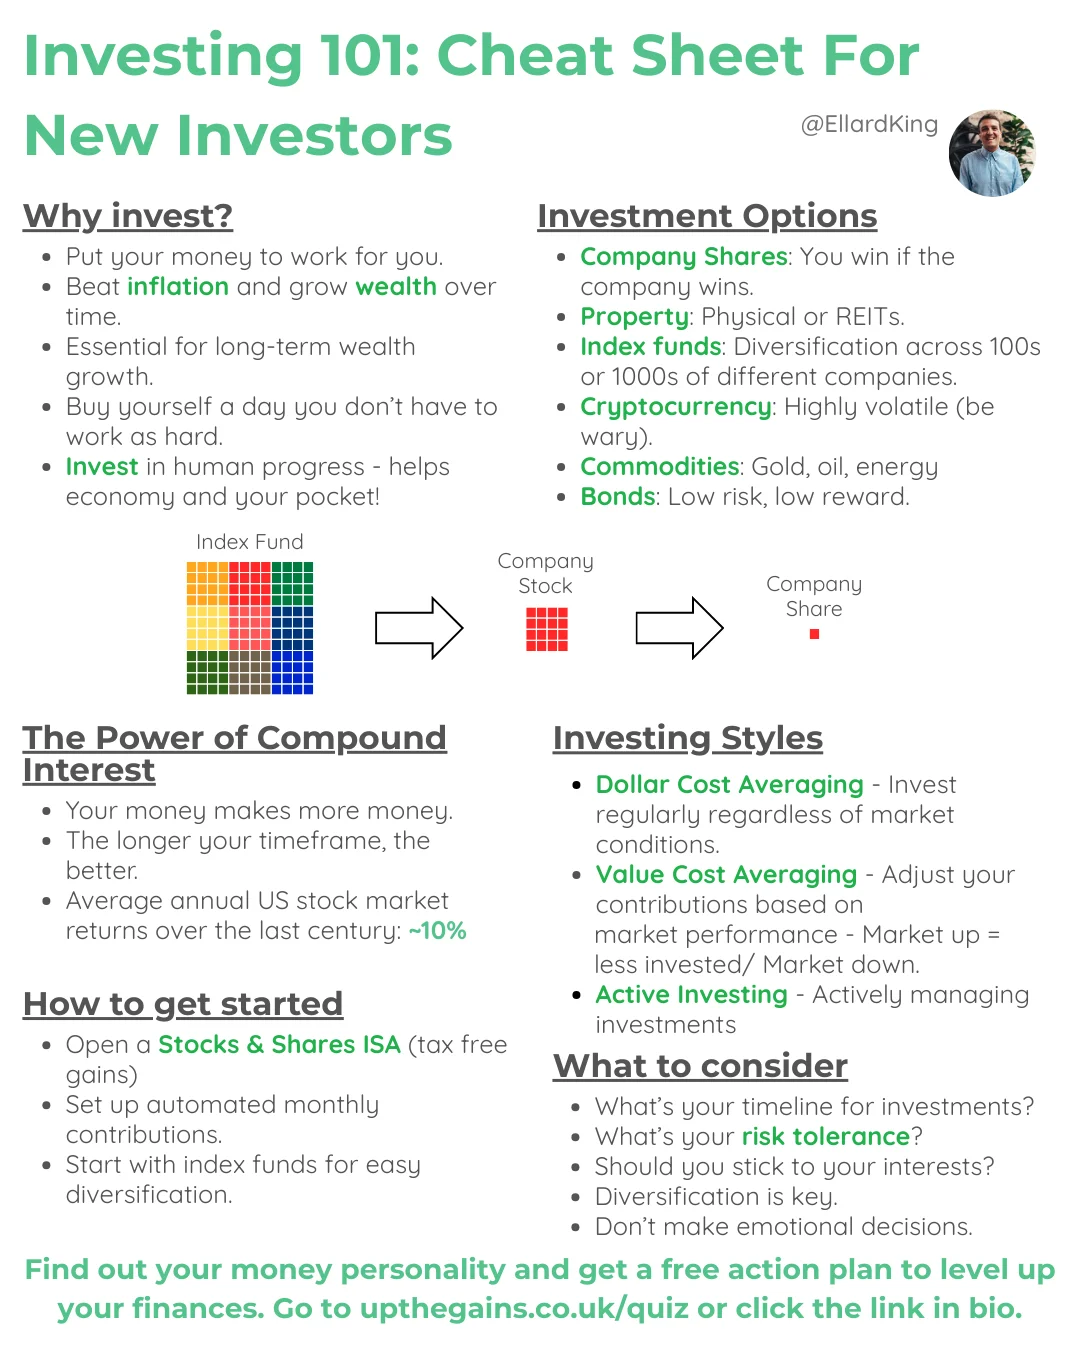
Instead of trying to pick winners, buy everything.
Every company in the market.
All of them. The good, the bad, the mediocre.
When the market goes up, you go up.
When it goes down, you go down.
But you capture all the market returns with minimal costs.
Why This Works
The market has trended up long-term. Over decades, stock markets have historically grown by roughly 5% to 8% a year on average. Past performance isn’t a guide to the future and growth isn’t guaranteed. Some years more. Some years less.
You own the winners automatically. Apple becomes massive? You own it. Some company you’ve never heard of explodes? You own it. Winners carry the portfolio.
Losers fade away naturally. Company goes bust? Index automatically removes it. You’re not stuck holding garbage.
Zero skill required. You don’t need to analyse companies. Don’t need to predict trends. Don’t need to time markets. Just buy everything and hold.
Index Funds vs Active Funds
Let’s compare the approaches directly.
Active Fund
Fees: 1.5% per year. Sometimes 2%. Plus performance fees if they beat benchmark.
Trading costs: Another 0.5-1% per year in hidden costs from buying and selling.
Manager risk: If star manager leaves, performance often crashes. You’re betting on one person.
Tax inefficiency: Lots of buying and selling triggers capital gains taxes outside ISA.
Time consuming: Need to research which fund to pick. Monitor performance. Switch funds when manager changes.
Performance: 92% underperform index over 20+ years.
Index Fund
Fees: 0.15-0.25% per year. Tiny fraction of active fund fees.
Trading costs: Minimal. Only trades when companies enter or leave index. Maybe 0.05% per year.
No manager risk: Automated. Nobody to leave. Rules-based. Consistent.
Tax efficient: Minimal trading. Fewer capital gains triggered outside ISA.
Time required: Pick once. Hold forever. Check maybe once per year.
Performance: Beats 92% of active funds over 20+ years.
Simple beats complicated. Low-cost beats high-cost. Passive beats active.
Full-time trader Michael Taylor reached the same conclusion on our podcast, explaining why a global tracker beats choosing between the S&P 500 and UK stocks.
 Read next5 Investing Podcast Episodes You Must Listen To
Why Fees Destroy Wealth
1% fee doesn’t sound like much. But it changes everything.
The Maths
Invest £350 per month for 30 years.
At 8% returns with 0.2% fee (net 7.8%): £500,927
At 8% returns with 1.5% fee (net 6.5%): £387,162
That 1.3% fee difference costs you £113,765 in final wealth. These are examples only: growth isn’t guaranteed.
Over £110,000 gone. Just in fees. For worse performance.
That’s not returns you missed.
That’s money taken directly from you for nothing.
Because remember: 92% of those expensive active funds underperform anyway.
You’re paying more for worse results.
Not sure where to start?
Pick your goal (debt free, start investing, side income, saving for something big) and get a free money plan you can level up on. Takes about two minutes.
Get your free money planThe ISA Wrapper: Keep The Tax Man Out
Making 8% returns is pointless if you lose 2-3% to taxes.
That’s where an ISA comes in.
Investing Outside as ISA
Capital gains tax: 18% or 24% on gains over the £3,000 allowance. Big portfolios get hit hard.
Dividend tax: 10.75% basic rate, 35.75% higher rate (2026/27) above the £500 allowance. Chunks of your returns gone.
Annual hassle: Report on tax return. Calculate gains. Track dividend income. Time consuming.
Over decades, taxes eat 1-2% of your returns. That compounds into massive losses.
Investing Inside a Stocks & Shares ISA
Capital gains: Zero tax. Ever. On unlimited gains.
Dividends: Zero tax. Whether basic or higher rate taxpayer.
Admin: Zero tax reporting needed. Set and forget.
Annual allowance: £20,000. For most people, that’s enough to invest everything.
The ISA wrapper is the most powerful tax shelter available. Use it.
The Long-Term Impact
£350 per month for 30 years at 8% returns equals £521,626 (an example only, growth isn’t guaranteed).
Outside ISA: Lose maybe 1.5% to taxes annually. Net 6.5% returns. End with £387,162.
Inside ISA: Keep all 8%. End with £521,626.
Tax savings: £134,464.
Same investments. Same contributions. Over £130,000 difference. Just from using ISA wrapper.
Best Sign-Up Offer
IG
Commission-free share dealing ISA with interest on cash
Offer: Free shares worth £40 to £300 when you invest at least £300 within 30 days and keep it invested for 3 months (code WELCOME300 or partner code). Capital at risk, T&Cs apply.
- £0 account fee and £0 commission
- 3.75% AER variable on uninvested cash (up to £100k)
- ISA, SIPP and Junior ISA available
- 0.7% FX fee on non-GBP trades
- Smart Portfolio SIPP carries a £210 annual fee
- Lower Trustpilot score than rivals (3.7)
- £1
- minimum
- £300 to qualify for the welcome offer
- Free
- platform fee
- ISA, GIA, Junior ISA, self-managed SIPP
- Free on UK and US shares with auto FX
- trading fee
- 0.7% FX fee
Affiliate link. Capital at risk.
The Simple Strategy Step-By-Step
Stop overthinking.
Here’s exactly what to do.
Step 1: Open Stocks & Shares ISA
Takes 20 minutes. Pick a provider.
Here is a list of the best free share offers so you can get a bonus just for starting.
Pick one. Open account. Verify identity. Done.
Step 2: Choose Low-Cost Index Fund
Don’t overcomplicate this. One or two funds maximum.
There are lots of index funds to choose from but you can pick to suit your preferences whether it’s localised, global or centered around one sector.
Global index funds are the complete solution.
Entire world’s stock markets in one fund.
Step 3: Set Up Monthly Contribution
Direct debit from your bank. Money moves automatically every month.
Start with whatever you can afford. £100, £200, £500. Just start.
Never see the money. Never make decision about investing. Happens automatically.
This is crucial. Automation beats willpower every time.
Step 4: Hold For Decades
Don’t check it daily. Don’t panic during crashes. Don’t sell when scary.
Check maybe once per quarter. Review annual statement. That’s it.
Markets will crash. Your portfolio will drop 30-40% sometimes. That’s normal.
People who keep investing through crashes get rich. People who sell in panic stay poor.
Step 5: Increase Contributions When Possible
Got a raise? Increase contribution by half the raise amount.
Paid off debt? Put those payments into investing.
Every increase compounds over decades. Makes massive difference to final wealth.
What About Picking Individual Stocks?
Don’t.
The Evidence
Research such as Brad Barber and Terrance Odean’s study of US share traders found that individual investors who trade the most tend to do worst.
Even worse than professional fund managers.
Because retail investors have even higher costs, worse discipline, and less information.
Why Stock Picking Fails
Overconfidence. You think you can spot winners. You can’t. Nobody can consistently.
Emotional decisions. You buy high because stock feels hot. Sell low because you panic.
Concentration risk. Own 5-10 stocks. One goes bust, you lose 10-20% of portfolio.
Time intensive. Need to research constantly. Read reports. Track news. It’s a part-time job.
Underperformance. After all that work, you do worse than if you’d just bought index fund.
The Bottom Line
92% of professional fund managers fail to beat the market over 20 years.
They have teams. Experience. Resources. They still fail.
You can beat them with five simple steps:
- Open Stocks & Shares ISA
- Buy low-cost global index fund
- Invest monthly automatically
- Hold for decades
- Ignore noise and keep going
This strategy costs 0.2-0.3% in fees. Theirs costs 1.5-2%.
This strategy requires zero skill. Theirs requires expertise they don’t have.
This strategy beats 92% of them. Consistently. Over decades.
Stop trying to pick winners. Stop trying to time markets. Stop paying high fees for worse results.
Buy everything. Pay minimal fees. Keep tax man out with ISA. Hold forever.
Simple beats complicated. Low-cost beats expensive. Passive beats active.
That’s how you outperform 92% of professional investors.
Not by being smarter. By being simpler. And cheaper. And more patient.
The professionals lose because they overcomplicate it. You win because you keep it simple.
Start today. Open the ISA. Buy the index fund. Let compound growth work for decades.
In 20-30 years, you’ll have outperformed 92% of the experts. Not because you’re better. Because your strategy is better.
That’s all it takes. Simple. Boring. Effective.
Want to go deeper on why simple, low-cost investing wins? These best investing books make the case better than we can.
If you found this interesting, please share!
Disclaimer: Content on this page is for informational purposes and does not constitute financial advice. Always do your own research before making a financially related decision.