Ever feel like your money vanishes the second it hits your account?
You’re not alone.
Millions of people watch their salary disappear into bills, expenses, and somehow… nothing left for them.
But here’s the thing: you are more important than your bills.
Yes, pay those bills.
But pay yourself first.
Sounds impossible? It’s not.
There’s a system that makes it automatic.
Meet The Three Bank System
This isn’t some complex financial wizardry.
It’s a simple setup that forces you to save without thinking about it.
Think of it like organising your kitchen.
Everything has its place.
Your money should work the same way.
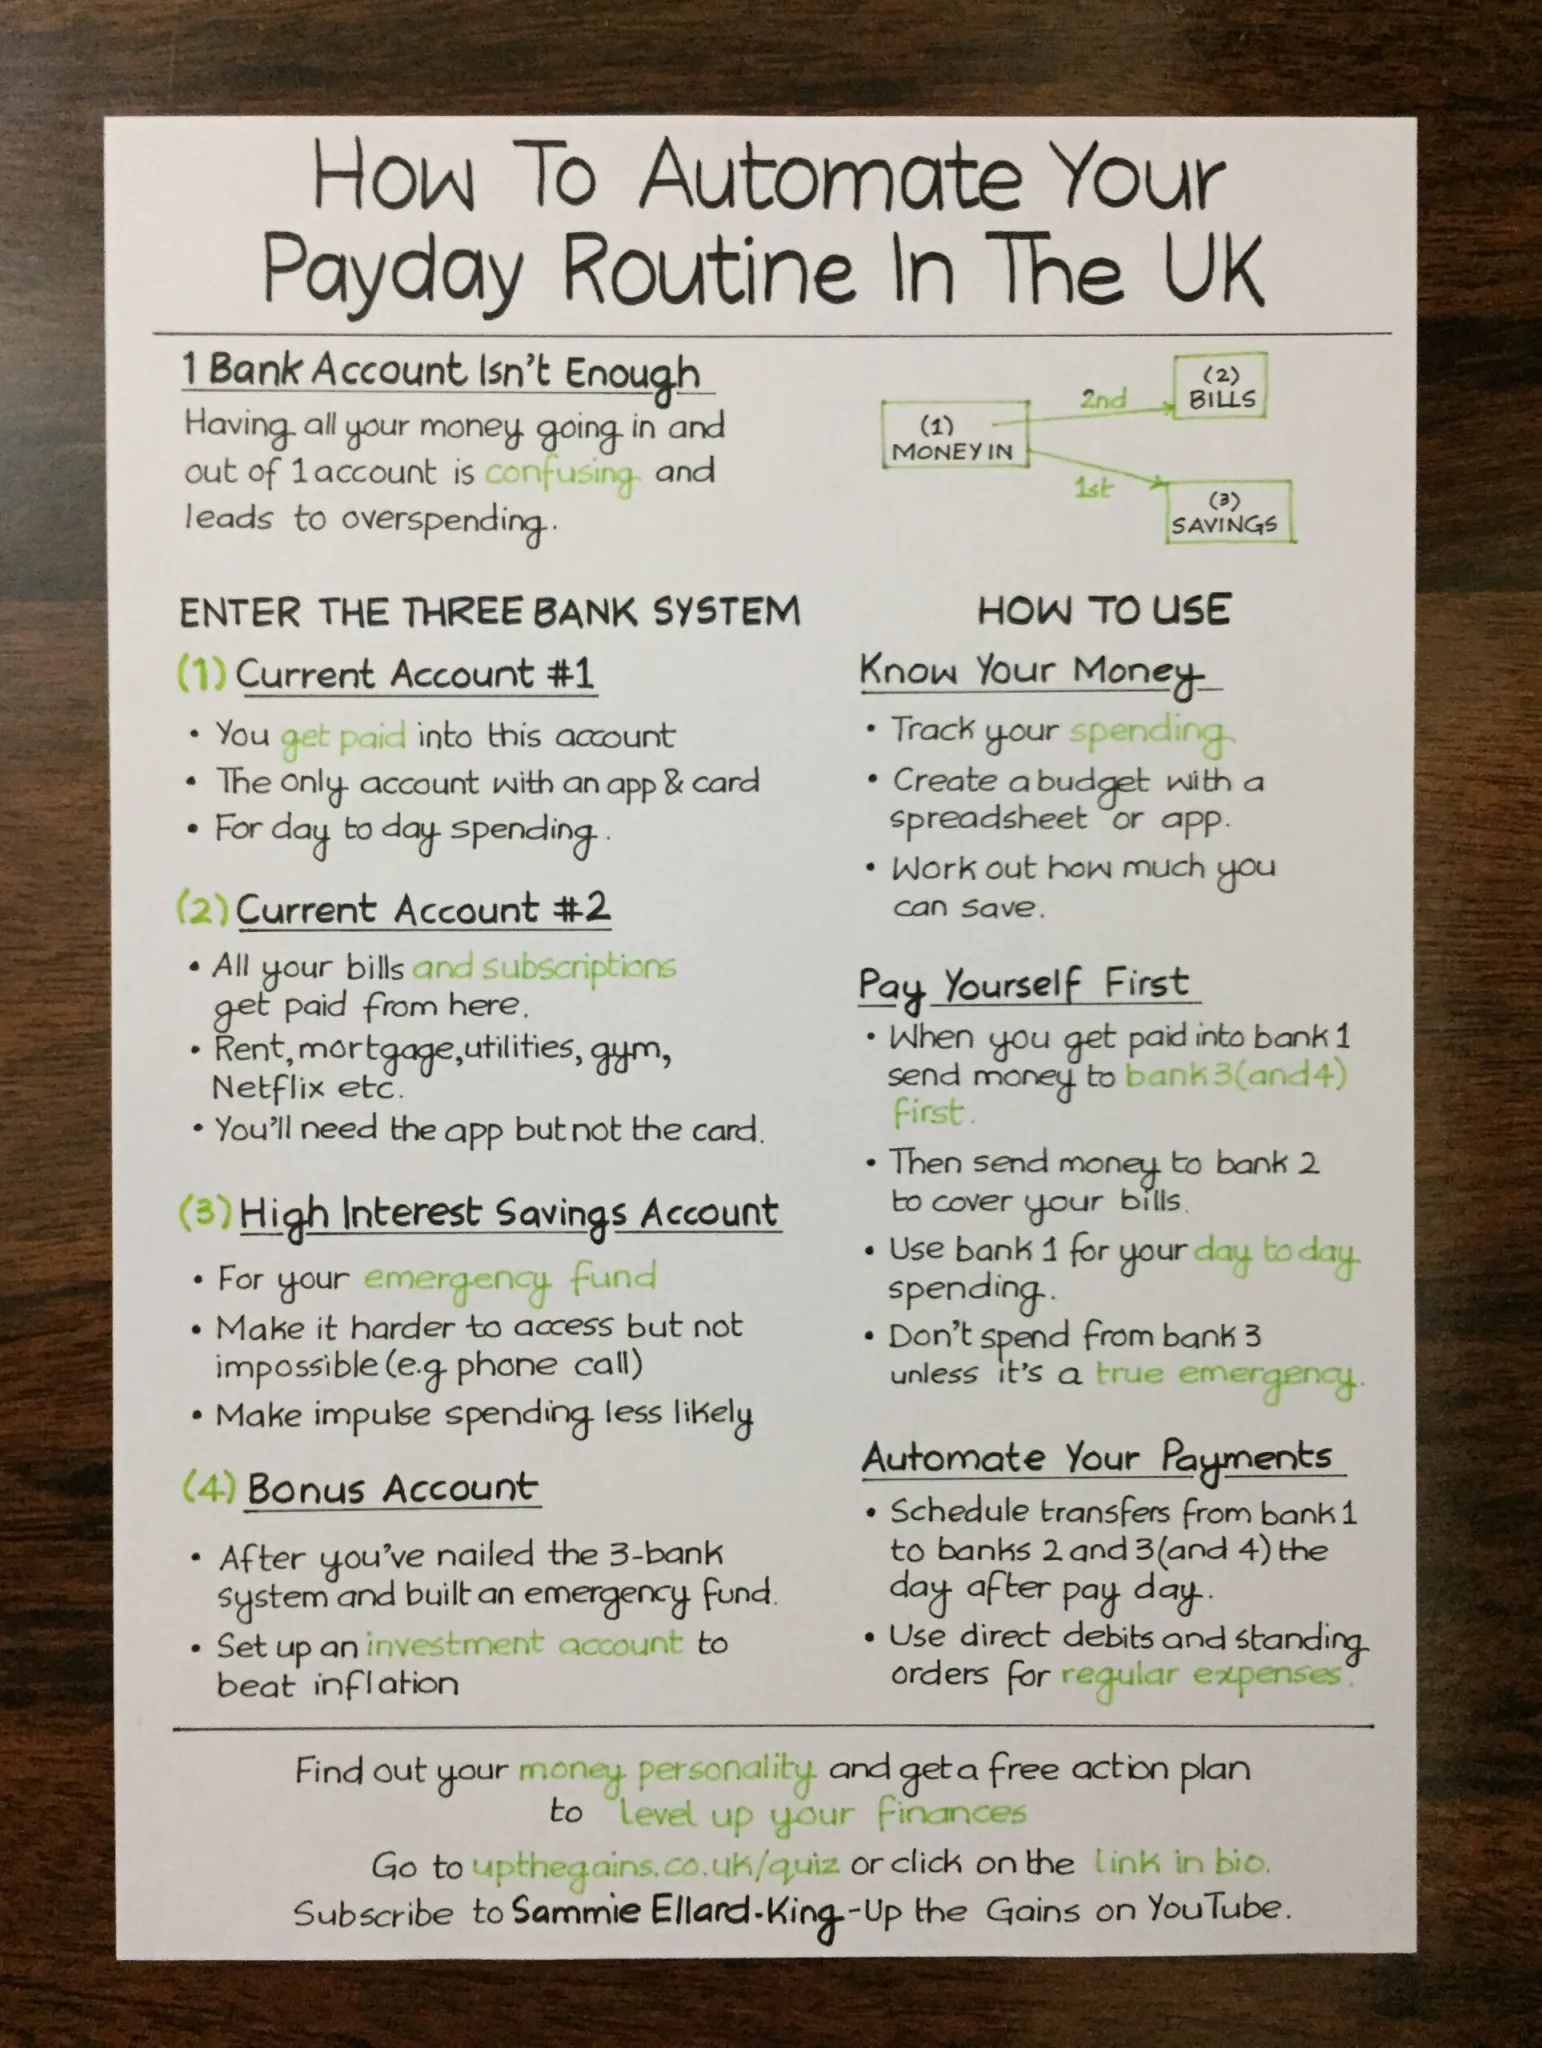
Bank 1: Your Salary Landing Pad
This is where your paycheck arrives every month.
It’s your main current account.
Keep the debit card and app for this one. You’ll need them.
But here’s the key: this account isn’t for storing money.
It’s a distribution centre.
Money comes in, gets sorted, and then moves out to where it needs to go.
What stays here?
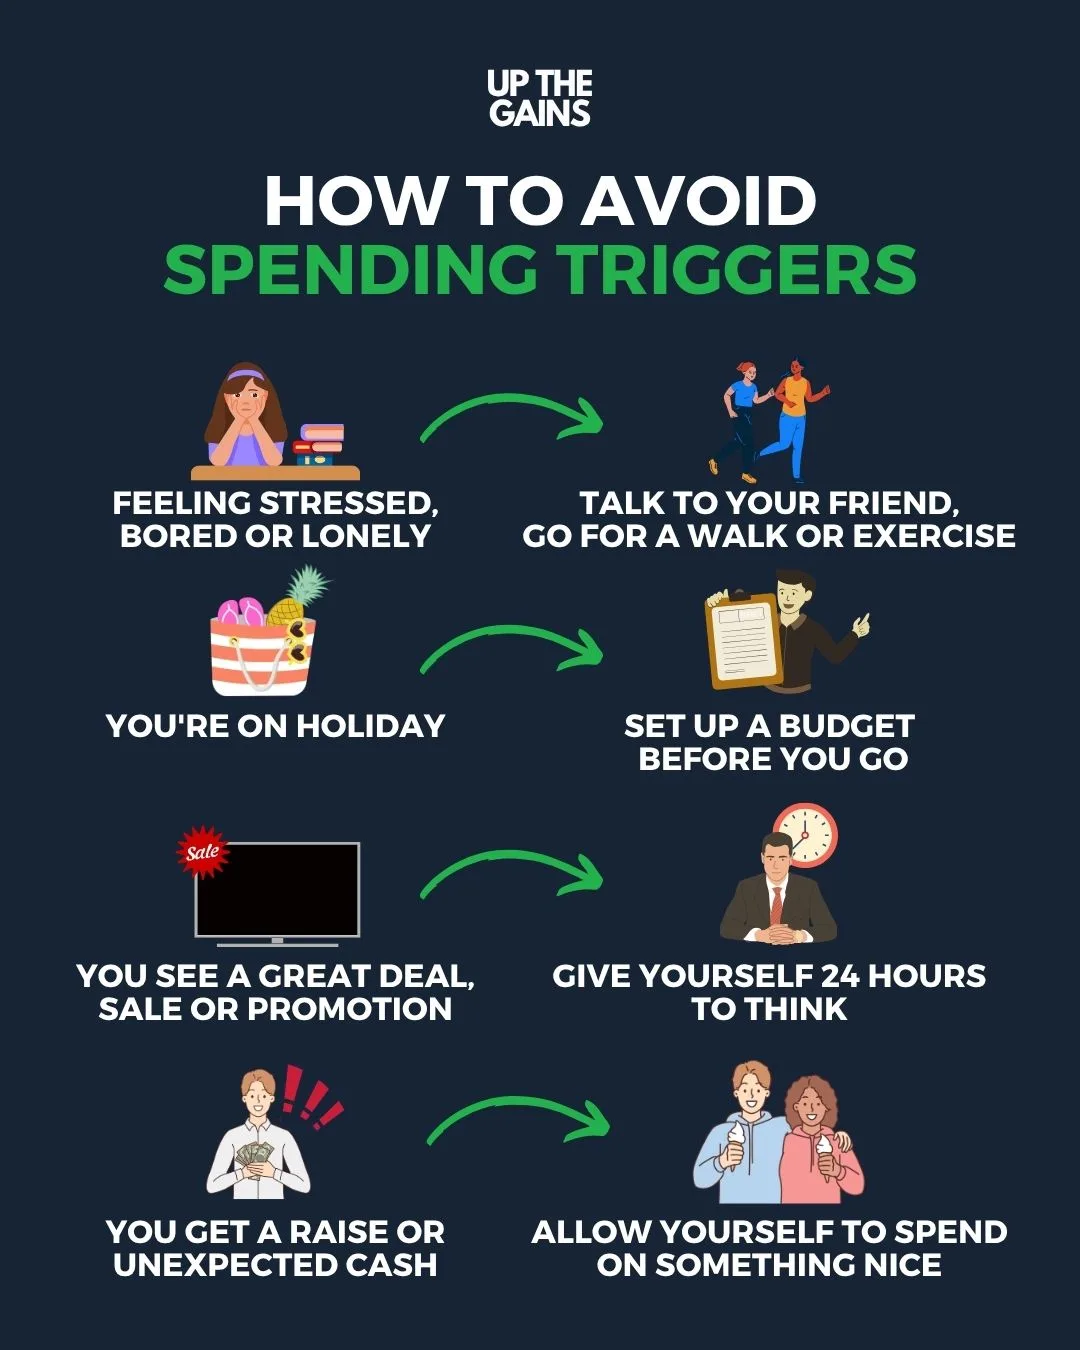
Your daily spending money.
Food, transport, that coffee you definitely need and the fun stuff that makes life worth living.
Bank 2: The Bill Paying Machine
Open a second current account.
This one handles all your boring but necessary expenses.
Rent, mortgage, utilities, subscriptions – they all get paid from here.
Set up the app so you can manage direct debits and standing orders easily.
But here’s the crucial part: no debit card for this account.
Why?
Because you don’t want to accidentally spend your bill money on a random shopping spree.
It removes temptation completely.
 Read nextIs Saving £100 A Month Good In The UK? (Savings Guide)
New to investing?
Get my free Checklist: the steps I would follow to open and fill an ISA without the classic mistakes. Plus one email a week, unsubscribe any time.
Bank 3: Your Financial Safety Net
This needs to be a high-interest savings account.
Not just any savings account – one that actually pays you decent interest.
This is where your emergency fund lives.
You know, that 3-6 months of expenses everyone talks about but nobody actually has?
Plus any other short to medium-term savings goals.
No app.
No card.
Nothing.
If you want to spend this money, you’ll need to call the bank or visit a branch.
This creates what we call a “spending speed bump” – just enough friction to make you think twice.
Chip
Savings and investing app with boosted easy-access rates
Affiliate link.
The Bonus Round: Bank 4
Once you’ve mastered the three-bank system and built your emergency fund, consider opening an investment account.
This is for long-term wealth building.
The money that’ll help you retire comfortably or buy that house you’ve been dreaming about.
Many people use a Stocks & Shares ISA for the tax benefits, and index funds are a common place to start.
They’re simple, effective, and you don’t need a finance degree to understand them.
Best ISA
Trading 212
Commission-free shares and ETFs in an ISA, Invest account or SIPP
Offer: Free fractional shares worth up to £100 with promo code GAINS (code must be used within 10 days of registering; value is random, most awards £8 to £25). Capital at risk, T&Cs apply.
- Commission-free trading, no account fee
- Pays interest on uninvested cash
- Stocks ISA and SIPP in one app
- CFDs in the same app: 77% of retail accounts lose money
- 0.15% FX fee each way on non-GBP trades
- Card deposits cost 0.7% after your first £2,000
- No Junior ISA or Lifetime ISA
- £1
- minimum
- Free
- platform fee
- Free
- trading fee
- 0.15% FX fee on non-GBP trades
Affiliate link. Capital at risk.
Not sure where to start?
Pick your goal (debt free, start investing, side income, saving for something big) and get a free money plan you can level up on. Takes about two minutes.
Get your free money planWhy This Actually Works
It’s all about paying yourself first.
When your salary hits Bank 1, you immediately send money to Bank 3 (and Bank 4 if you have it).
Then you fund Bank 2 for bills.
Whatever’s left is your spending money.
You’re literally putting your future self ahead of everything else.
It’s not reckless – it’s strategic.
Making It Automatic
The beauty of this system?
You can set it and forget it.
- Automate your bill payments from Bank 2
- Schedule regular transfers to savings and investments
- Use direct debits for predictable expenses
- Set up balance alerts to avoid nasty surprises
Once it’s running, you barely need to think about it.
Your money sorts itself.
You’ll Need to Budget Like a Pro
This system only works if you know your numbers.
How much goes to bills?
How much can you realistically save?
What do you need for daily life?
Use a budgeting app or spreadsheet to figure this out.
Without a budget, you’re flying blind.
The goal isn’t to be perfect.
It’s to be intentional with your money.
You can find my suggestions for budgeting apps here.
Best For Budgeting
Snoop Money
Free budgeting app that tracks every account and finds savings
- Free open-banking budgeting across all accounts
- Bill and subscription tracking
- Personalised money-saving deals
- Savings withdrawals after 11am are actioned the next working day
- FSCS £120,000 limit is shared with any money you hold at Vanquis
- No ISAs or investing
- Some features need Snoop Plus (£5.99 a month or £47.99 a year)
- Cost: Free
- cost
- Free
- fee
- Snoop Plus £5.99/mo or £47.99/yr
Affiliate link.
Your Money, Your Rules
Look, this system isn’t magic. It won’t solve every financial problem overnight.
But it will do something more important: it’ll make saving automatic.
When saving becomes a habit instead of a struggle, everything changes.
You’ll stop feeling guilty about that emergency fund that doesn’t exist.
You’ll stop worrying about next month’s rent.
You’ll actually start building wealth instead of just surviving.
The three-bank system puts you back in control.
Your money works for you, not the other way around.
Ready to stop letting your paycheck slip through your fingers?
If you’re still not sure what steps to take next, get a free money action plan by taking this quiz.