When you invest, your capital is at risk.
Most people think you need thousands of pounds to start investing. You don’t.
£100 is enough to open a real investment account, buy into thousands of companies around the world and start building the habit that does the heavy lifting over time. I started small too, and the hardest part was simply getting going.
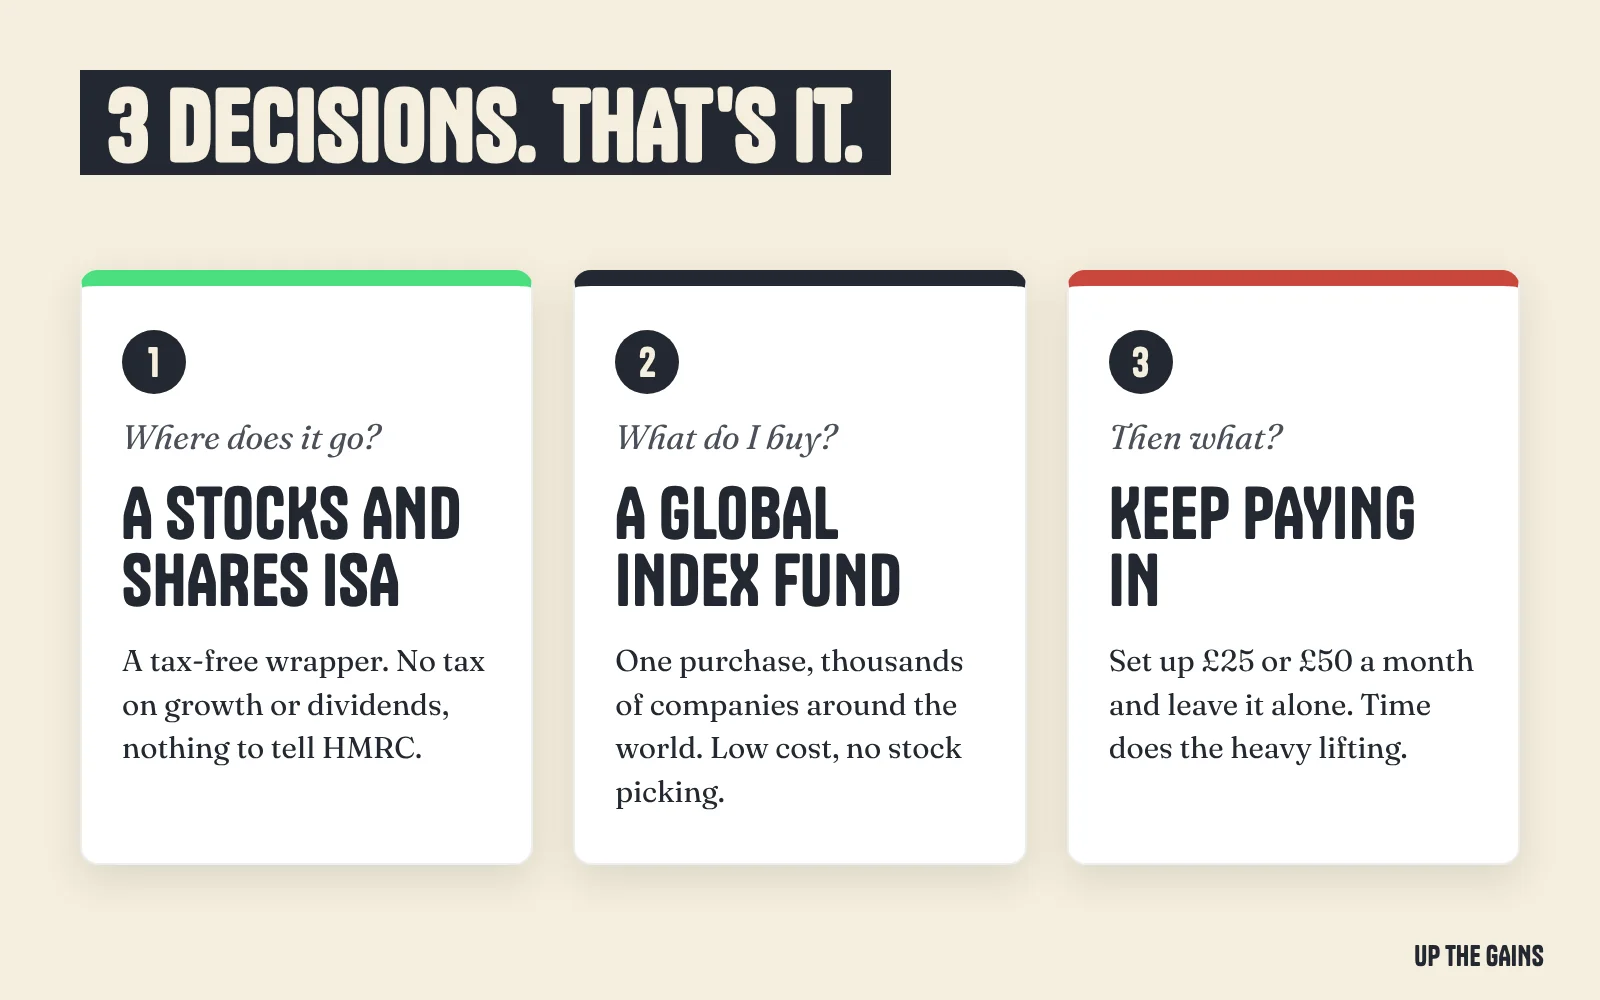
This is the no-jargon version, and it comes down to three decisions: where to put your money, what to buy with it, and how to keep it ticking over. By the end of this guide you could have your first £100 invested today.
The short version
- Open a stocks and shares ISA, so everything you make is tax free.
- Put your £100 into a global index fund, so it is spread across thousands of companies.
- Set up £25 or £50 a month and leave it alone for at least five years.
- Pick a platform with low minimums and no flat monthly fee.
Why invest your £100 at all?
Cash feels safe, and for money you might need in the next few years it is the right home. But left in a low-interest account, £100 slowly loses value, because prices tend to rise faster than most savings rates. That is inflation quietly shrinking what your money can buy.
Investing flips that. Your £100 buys a small stake in real companies that grow, pay dividends (a share of their profits) and reinvest what they make. Over the years, those returns start earning returns of their own. That is compounding, and the biggest advantage you have is time.
As an illustration: if you invested £100 today, added £50 a month and it grew by 5% a year after fees, after 20 years you would have paid in £12,100 and could have around £20,800. Growth isn’t guaranteed, and you could get back less than you put in. Try your own numbers in the compound interest calculator.
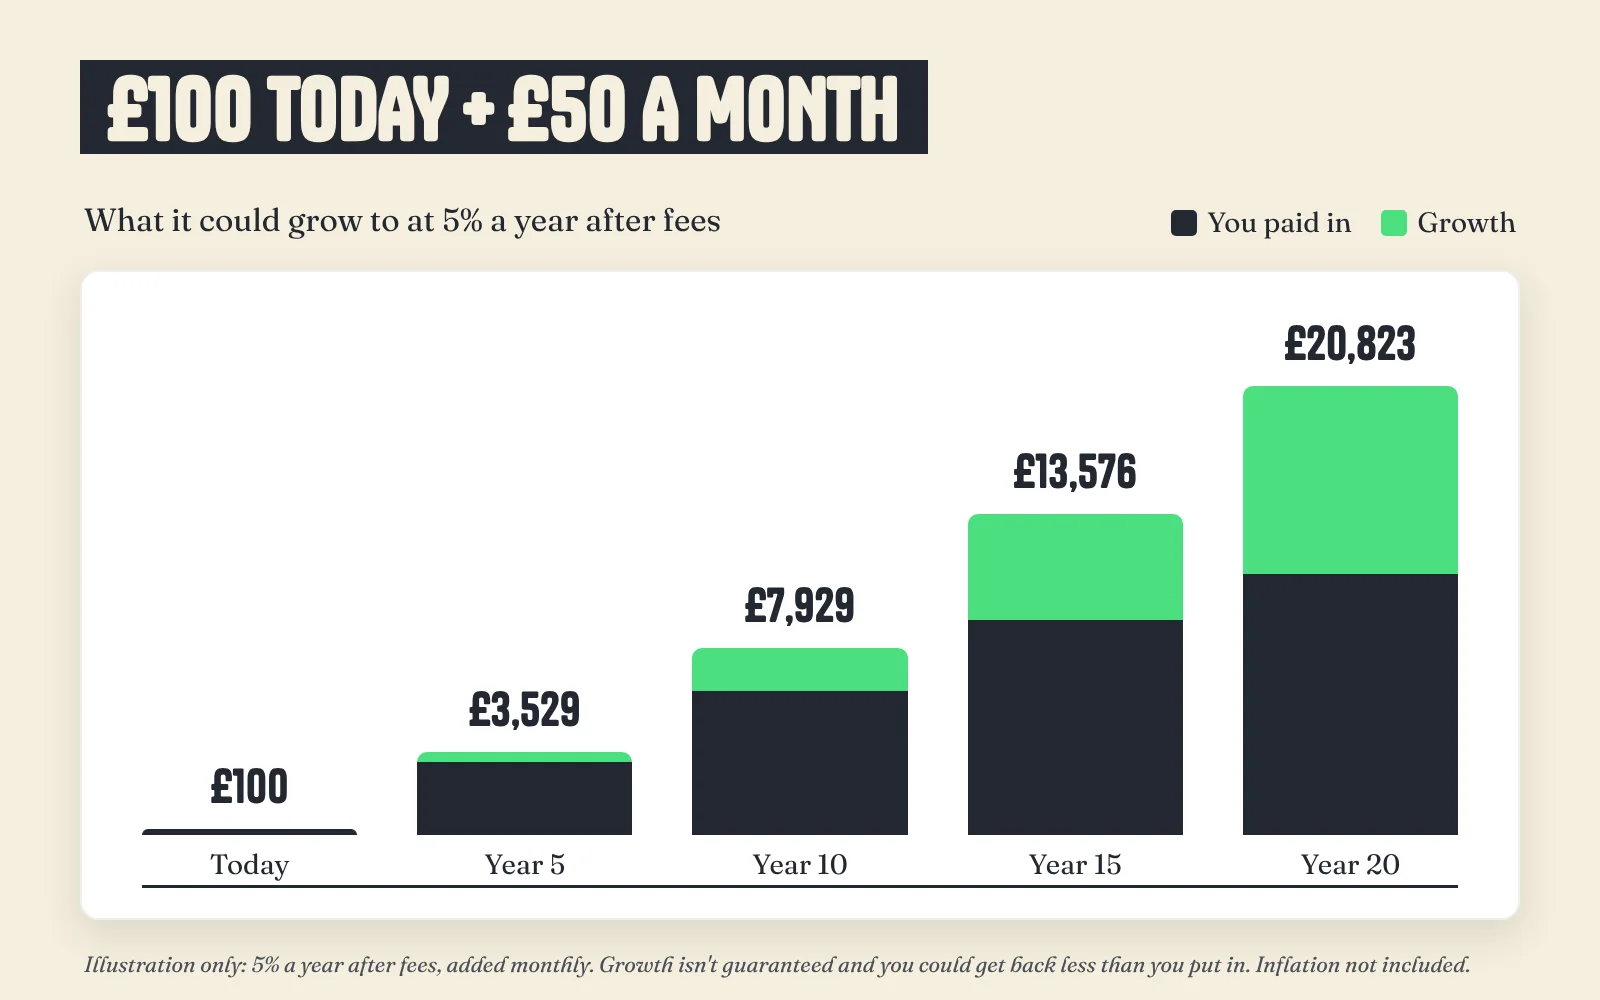
Starting with £100 today beats waiting until you have “enough”, because time is the one thing you can’t buy back later.
Before you start: two quick checks
Investing works best with money you can leave alone for at least five years. So before you put anything in, check these two things.
- Do you have an emergency fund? A pot of easy-access cash for surprise bills means you won’t have to sell investments at a bad time. Here’s how much should be in your emergency fund.
- Do you have expensive debt? Credit cards and overdrafts usually charge more interest than investing is likely to earn, so clearing them first often makes sense. I cleared £24,000 of debt in my twenties, and this is how I did it.
Step 1: Pick the right account
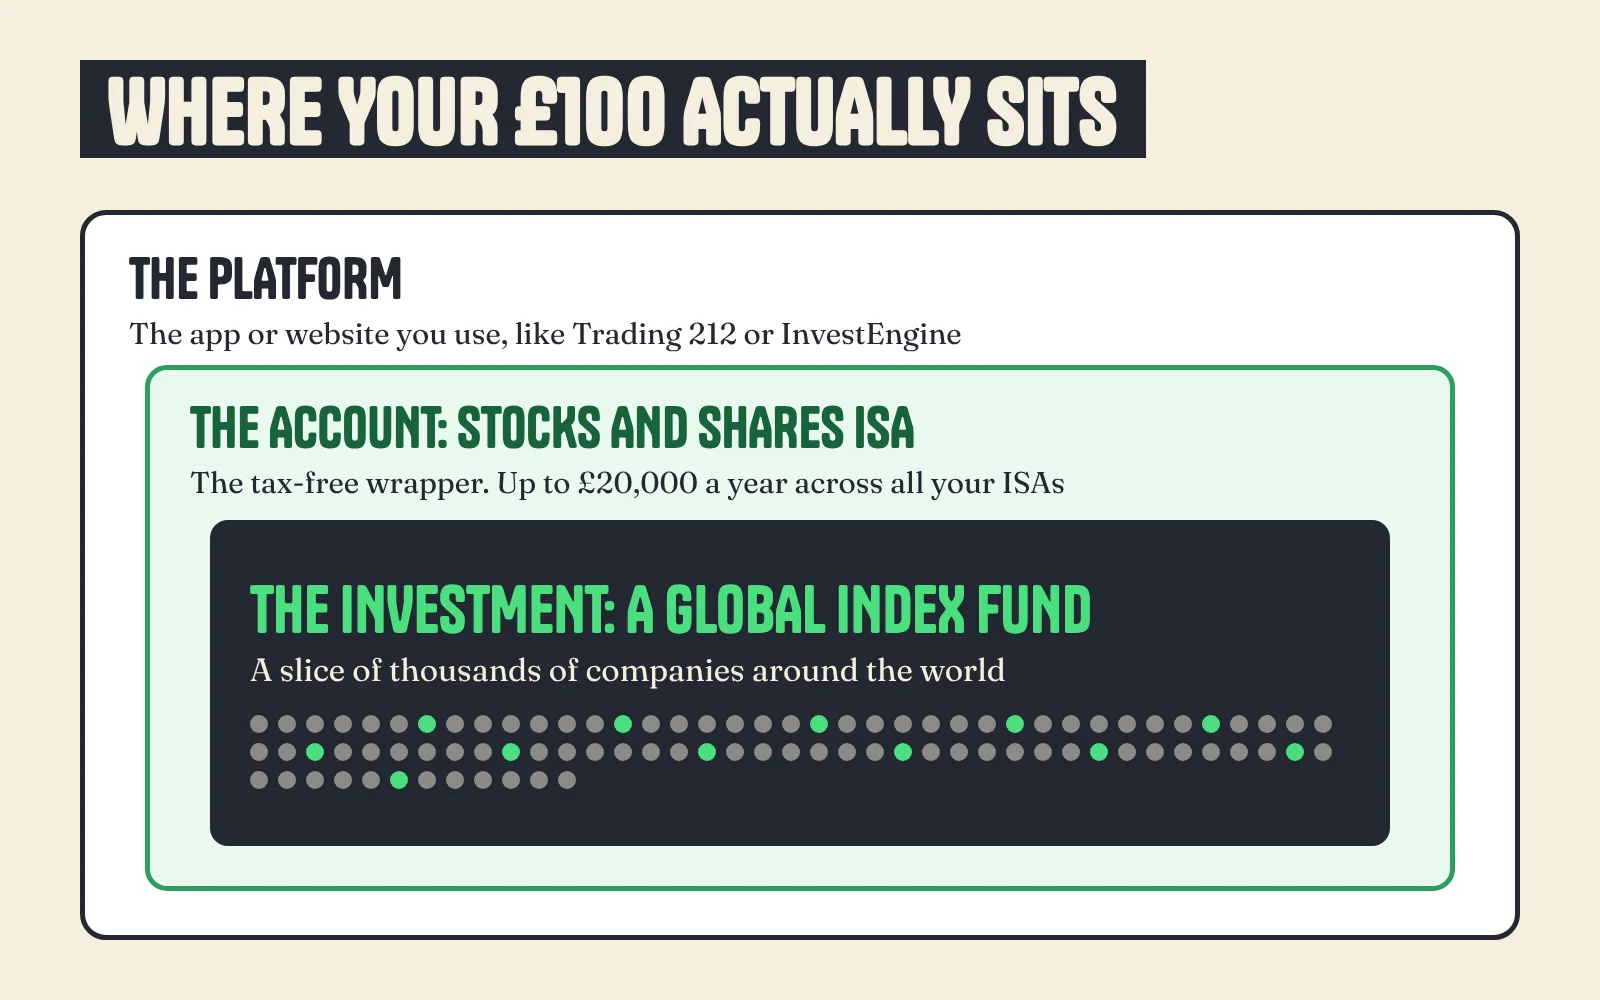
There are two parts to where your money goes: the account (the wrapper your money sits in) and the platform (the app or website you use). Get the account right first, because it decides how much tax you pay on what you make.
For most beginners, it’s a Stocks and Shares ISA
A Stocks and Shares ISA is a tax-free wrapper for investments. Any growth, dividends or profit inside it is yours to keep, with no tax to pay and nothing to report to HMRC. Here’s how a Stocks and Shares ISA works in more detail.
You can pay in up to £20,000 each tax year across all your ISAs, so £100 leaves you plenty of room. The tax year runs from 6 April to 5 April, and your allowance resets each April. ISA rules are due to change from April 2027, so it’s worth reading what the 2027 ISA changes mean.
What about other accounts?
- Lifetime ISA: if you are saving for your first home, the government adds a 25% bonus. Read how a Lifetime ISA works before you choose, because there are penalties if you take money out for anything else.
- Pension: great for the long term thanks to tax relief, but you can’t usually touch it until later in life. See SIPP vs ISA; a SIPP is a personal pension you run yourself.
- General Investment Account: no tax wrapper, so it’s usually only worth it once your ISA allowance is full. Here’s how it compares.
Step 2: Pick a platform
The platform is where you open your ISA and buy your investments. With £100, a few things matter far more than fancy features.
- Low minimums: look for a platform that lets you start with £100 or less, and invest small regular amounts.
- Fractional shares: these let you buy a slice of a share instead of a whole one, so your £100 actually gets invested rather than being too little for one expensive share.
- Fees that suit a small pot: more on this below, because fees can quietly eat a beginner’s returns.
- Regulation and protection: make sure the platform is authorised by the Financial Conduct Authority (FCA), the UK’s financial regulator, and covered by the Financial Services Compensation Scheme (FSCS).
- An app you’ll actually use: if it’s easy to set up a monthly payment, you are far more likely to keep going.
Here are the platforms that work well for a £100 start, side by side:
- Minimum
- £1
- Platform fee
- Free
- Trading fee
- Free0.15% FX fee on non-GBP trades
- Minimum
- £100
- Platform fee
- FreeDIY; Managed closed to new clients
- Trading fee
- FreeNo commission, no FX fee
- Minimum
- n/a
- Platform fee
- FreeBasic; Standard £4.99/mo, Plus £9.99/mo billed annually
- Trading fee
- £0 commissionFX fee 0.99% Basic / 0.59% Standard / 0.39% Plus
- Minimum
- £1
- Platform fee
- Free
- Trading fee
- Free0.1% FX fee
Last checked 10 November 2026. Fees and offers change, so check before you open an account. Some links are affiliate links: we may earn a commission at no cost to you. Capital at risk.
Fees: the bit most beginners miss
Investing platforms can charge in a few ways, and they add up:
- Platform fee: what the platform charges to hold your account, either a percentage of your pot or a flat monthly fee.
- Fund fee: called the ongoing charge, this is taken by the fund itself. Index funds are usually among the cheapest.
- Trading fees: a charge each time you buy or sell. Many apps now charge nothing here.
- Currency fees: charged when you buy shares priced in another currency, such as US shares.
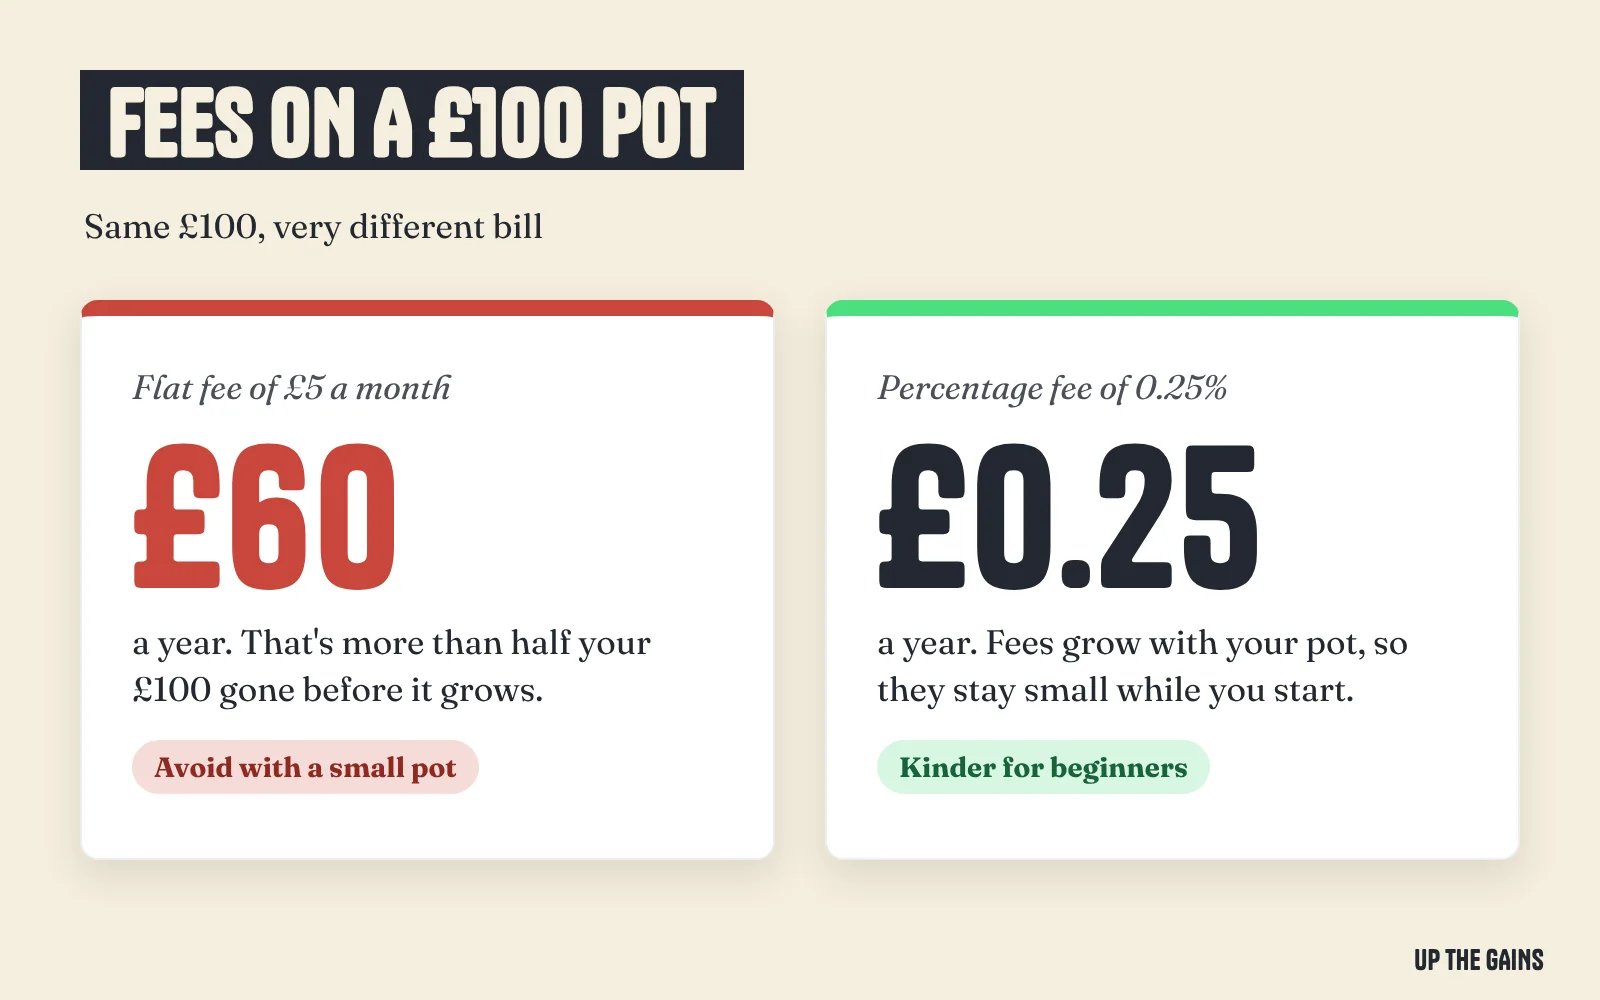
With a small pot, percentage fees are usually kinder than flat ones. A £5 a month flat fee is £60 a year, which would wipe out more than half of a £100 investment. A 0.25% fee on £100 is 25p a year.
To weigh up the options, compare the main UK platforms side by side with our comparison tool, or see my pick of the best Stocks and Shares ISAs and best investing apps.
What FSCS protection does and doesn’t cover
If an FCA-authorised investment platform goes bust and your money can’t be returned, the FSCS can usually cover up to £85,000 per person, per firm. It does not protect you if your investments simply fall in value. That’s the normal risk of investing.
Step 3: Choose what to invest in
This is where beginners freeze, so keep it simple: don’t try to pick the next big winner. One company can sink. Thousands of them together rarely do.
Index funds vs single shares
An index fund is a fund that tracks a list of companies, such as the FTSE 100 (the 100 biggest companies on the London Stock Exchange) or a global index of thousands of companies around the world. You’ll often see them as ETFs, which stands for exchange-traded funds: funds you buy and sell like a share.
| Global index fund | Single shares | |
|---|---|---|
| What you own | A small slice of thousands of companies | A slice of one company |
| Risk | Spread out, so one company falling barely matters | If that company struggles, so does your £100 |
| Research needed | Very little | A lot, and it never stops |
| Cost | Usually low ongoing charges | Often free to buy, but watch currency fees |
| Good for beginners? | Yes, the classic first investment | Only with money you can afford to lose |
The classic beginner choice is a global index fund. In one purchase it spreads your £100 across thousands of companies all over the world, so you are backing global business growing over time rather than gambling on one stock. It is low cost, needs no daily attention and is exactly what fractional investing was made for. Read how to invest in index funds in the UK before you buy.
Fractional shares, explained
Some shares cost hundreds of pounds each. Fractional shares let you buy part of one, so £10 can buy a tenth of a £100 share. That means every pound of your £100 gets invested, whether you buy a fund or a share.
Accumulation or income?
Many funds come in two versions. Accumulation (often shown as Acc) automatically reinvests any dividends for you, which is the simple way to let compounding do its job. Income (Inc) pays dividends out as cash instead.
New to investing?
Get my free Checklist: the steps I would follow to open and fill an ISA without the classic mistakes. Plus one email a week, unsubscribe any time.
Step 4: Set it up and keep it going
Open the account, add your £100 and make your first purchase. The setup takes minutes.
Then comes the part that actually builds wealth: keep going. Set up a small regular payment, even £25 or £50 a month, and let it invest automatically. Paying in steadily means you buy at lots of different prices over time, which smooths out the ups and downs.
You don’t need to watch the market, time anything or check it every day. In fact, the less you fiddle, the better you tend to do.
Top tip: set your monthly payment to go out the day after payday. The money is invested before you have a chance to spend it, and you never have to remember to do it.
Common beginner mistakes
- Investing money you’ll need soon. Keep at least five years in mind.
- Chasing hot tips. If everyone online is shouting about one share, you are probably late.
- Selling in a panic. Markets fall sometimes. Selling during a dip locks in the loss.
- Ignoring fees. On a small pot, the wrong fee structure can cost more than you make.
- Checking every day. It’s a years and decades game. Daily checking mostly leads to bad decisions.
Quick questions before you start
Is £100 too little to bother?
No. Thanks to fractional shares and low or no trading fees on many platforms, £100 starts exactly the same machine as £10,000, just smaller. The habit is worth more than the amount you begin with.
Is investing risky?
Your money can go down as well as up, yes, and you may get back less than you put in. Spreading it across a global fund and leaving it invested for years is how beginners manage that risk sensibly.
Do I have to use an ISA?
No, but for most people it’s the obvious choice, because the growth is tax free. There is rarely a good reason for a beginner to skip it.
Can I take my money out?
Usually, yes. You can sell your investments and withdraw the cash, though it can take a few days and you might get back less than you put in. Money you take out doesn’t give you that allowance back unless your ISA is a flexible ISA, so check with your provider.
What happens if the platform goes bust?
Your investments are held separately from the platform’s own money. If something does go wrong and money can’t be returned, FSCS protection can usually cover up to £85,000 per person, per firm. It doesn’t cover your investments falling in value.
How soon will I see returns?
Investing is a years and decades game, not a weeks one. Judge it over the long run, not on what it does next month.
Your next step
That’s the whole thing: open a Stocks and Shares ISA, buy a global index fund and keep paying in. Three decisions, £100, and you could be done today. Start by choosing from the best Stocks and Shares ISAs.
Want to keep learning on the go? Tune into my pick of the best investing podcasts.