GoHenry is a prepaid debit card and app for children aged 6 to 18, run by a parent who sets the limits, sees every payment and can pay pocket money automatically. It costs £3.99 a month per child on the Everyday plan, £5.99 per child on Plus, or £9.99 a month for up to four children on Max, with the first month free (checked 10 November 2026). The catch is the cost: unlike some rivals, it’s never free.
I rated GoHenry 4.25 out of 5 with our six pillar method, scoring best for useful features, user experience and suitability for beginners, and lowest on price. Money on the card is e-money held in a protected client account, not a bank account, so it isn’t covered by the FSCS (the UK’s compensation scheme).
Best for teaching kids about money
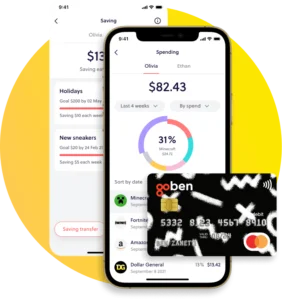
GoHenry
Debit card and money app for kids
Offer: One month free (all plans)
- Never free: £3.99 a month per child on Everyday
- Free month renews automatically unless you cancel
- Everyday: 50p for every top-up after the first each month
- Card money is e-money, not FSCS protected
- £3.99/mo per child
- fee
- Everyday, £5.99 (Plus), £9.99 up to four kids (Max)
Affiliate link.
GoHenry review: my verdict at a glance
| GoHenry (checked 10 November 2026) | |
|---|---|
| My rating | 4.25 out of 5 |
| Best for | Parents who want a kids card with strong controls, chores and money lessons in one app |
| Ages | Children 6 to 18; parent must be 18 or over and live in the UK |
| Plans | Everyday £3.99 per child, Plus £5.99 per child, Max £9.99 for up to four children (a month) |
| Free trial | One month, then renews automatically unless you cancel |
| Top-ups | Everyday: first load each month free, then 50p. Plus and Max: free |
| Savings interest | 2.63% AER (variable) on Plus and Max only |
| Junior ISA | Stocks and Shares Junior ISA, 0.45% a year plus a 0.22% fund charge |
| Protection | Card money: e-money, not FSCS. Interest savings: FSCS up to £120,000. Junior ISA: FSCS up to £85,000 if a firm fails |
| Trustpilot | 4.0 out of 5 from 12,308 reviews |
Having played around with the app, I think the cost is worth it for what it teaches kids about how money works. It gets a big tick from me.
Who GoHenry suits (and who it doesn’t)
GoHenry suits you if
- You want your child to have their own card, while you control where and how much they spend.
- You want to pay pocket money automatically and link it to chores.
- You want built-in money lessons for your child, not just a card.
- You have two or more children and would use the Max plan, which covers up to four for one price.
Look elsewhere if
- You don’t want to pay a monthly fee: some kids cards and accounts don’t charge one.
- You want the money to be in an FSCS-protected bank account.
- You top up little and often on the Everyday plan, where every load after the first each month costs 50p.
- Your child is under 6, or about to turn 18 (the card closes at its expiry date after 18).
How GoHenry works
You sign up as the parent, either in the app or on GoHenry’s website, and add up to four children per parent account. You load money into your parent account from your bank or card, then move it to each child instantly and free. Each child gets a Visa debit card, which they can use in shops, online and, if you allow it, at cashpoints.
- Pocket money and chores: set a weekly allowance, or pay for tasks once they’re done.
- Giftlinks: family and friends can send money straight to your child.
- Savings goals: your child can set money aside for something they want.
- Money Missions: 100+ short lessons on saving, borrowing, investing and more.
- Co-parent: you can invite one other adult to share the parent account.
For more ideas on building good habits early, see how to teach kids about money and our games that teach kids about money.
New to investing?
Get my free Checklist: the steps I would follow to open and fill an ISA without the classic mistakes. Plus one email a week, unsubscribe any time.
GoHenry parental controls
This is where GoHenry stands out. As the parent you can:
- Set spending limits for a single payment and for each week.
- Choose where the card works: online, in shops and at cashpoints, switching each on or off.
- Get instant notifications every time your child spends or withdraws cash.
- Freeze or block the card straight away if it’s lost.
- Rely on automatic adult blocks: the card won’t work at gambling sites and betting shops, vape and tobacco shops, adult entertainment and similar 18+ businesses.
One limit worth knowing: the adult blocks rely on how each shop registers with Visa. GoHenry’s own terms give the example that a corner shop registered as a tobacconist will be blocked, but the same shop registered as a grocer won’t. So the blocks are a backstop, not a guarantee.
How much does GoHenry cost?
GoHenry is a subscription. These are its plans and fees, from its pricing page and its cardholder terms (version 10.1, April 2026):
| Everyday | Plus | Max | |
|---|---|---|---|
| Monthly cost | £3.99 per child | £5.99 per child | £9.99 for 2 to 4 children |
| Cost per year | £47.88 per child | £71.88 per child | £119.88 |
| Loading your parent account | First load each month free, then 50p | Free | Free |
| Interest on savings | No | 2.63% AER | 2.63% AER |
| Card, app, chores, Money Missions, Junior ISA | Yes | Yes | Yes |
Other fees from GoHenry’s terms:
- Standard card free; personalised designs from £4.99.
- Lost, stolen or damaged card replaced free with the same design; a new design costs £4.99.
- No GoHenry fees on cash withdrawals or card payments, in the UK or abroad, though a cashpoint owner can charge.
- 50p service charge if your monthly fee has to be taken from your bank because your parent balance is too low.
- £2.50 a month on dormant accounts, and £5 to send money back to your bank through member services instead of the app.
Is GoHenry worth the money?
The sums (my arithmetic on GoHenry’s prices): one child on Everyday is £47.88 a year. Two children cost £95.76 on Everyday or £119.88 on Max, so Max costs £24.12 a year more but brings free top-ups and savings interest for both. With three children, Max (£119.88) is cheaper than Everyday (£143.64), and with four it saves £71.64 a year. If you top up weekly on Everyday, the 50p loads add about £20 a year.
We’re not big fans of the fact that GoHenry is never free, and there are kids cards with no monthly fee. But I think the features make it worthwhile for the education alone. Personally, it’s worth it knowing your child is spending safely and learning along the way.
 Read nextMoneybox Review 2026 – Pros & Cons (Personally Tested)
GoHenry savings interest and Junior ISA
Interest Savings
On Plus and Max, your child can move money into an Interest Savings pot paying 2.63% AER (variable). That money goes through a partner, Bondsmith, into a bank account, so it’s covered by the FSCS up to £120,000 if the bank fails. Money on the card itself earns no interest. If you drop back to Everyday, your child can’t add more and the rate on what’s left goes down.
GoHenry Junior ISA
When you invest, your capital is at risk.
Every plan can open a Stocks and Shares Junior ISA from £1, paying in up to £9,000 in the 2026/27 tax year. The money goes into a single fund, Vanguard LifeStrategy 60% Equity, which is about 60% shares and 40% bonds. GoHenry charges 0.45% a year plus Vanguard’s 0.22% fund charge, so £1,000 would cost about £6.70 a year. The ISA manager is Seccl Custody Limited, and GoHenry Limited is FCA authorised for this (FCA number 1013107).
The money belongs to your child and is locked until they turn 18, when it becomes theirs to keep, spend or move into an adult ISA. If your child has a Child Trust Fund, you’ll need to transfer it in first. With only one fund to choose from, it’s simple but limited; our best Junior Stocks and Shares ISA comparison and what is a Junior ISA guide cover the wider choice.
Is GoHenry safe?
GoHenry isn’t a bank, and the card account isn’t covered by the FSCS. Here’s how each part is protected:
- Card and parent account money is e-money issued by IDT Financial Services Limited, a bank licensed by the Gibraltar Financial Services Commission. GoHenry runs the app and support for IDT. IDT holds your money in a secure client account that’s protected from its creditors if it goes bust, but the Gibraltar deposit guarantee scheme doesn’t apply because it isn’t a deposit.
- Interest Savings money sits in a bank account through Bondsmith, with FSCS cover up to £120,000.
- The Junior ISA is covered by the FSCS up to £85,000 if a firm fails, but never against investments falling in value.
- Card security: a Visa youth card with parent notifications, freezing in the app and automatic blocks on 18+ businesses.
For pocket money, that protection is reasonable. It’s still sensible not to leave large sums on a card account. You can check any provider with the FSCS protection checker.
Opening and cancelling a GoHenry account
- You must be 18 or over and live in the UK. Sign up in the app or on GoHenry’s website with your details and your children’s details.
- Make a first payment into your parent account, then activate each child’s card in the app when it arrives in the post. GoHenry only posts cards to UK addresses.
- Your membership starts when you activate the parent account, and the free month then rolls into your paid plan.
- You have 14 days to cool off after signing up. After that you can cancel any time, with no cancellation fee, in the app or by contacting GoHenry’s member services. Any money left is returned to you, usually within 7 to 10 working days.
When a child turns 18 they can keep using their card until it expires, then their GoHenry account closes.
Not sure where to start?
Pick your goal (debt free, start investing, side income, saving for something big) and get a free money plan you can level up on. Takes about two minutes.
Get your free money planGoHenry reviews: what customers say
On Trustpilot’s UK GoHenry profile, it scores 4.0 out of 5 from 12,308 reviews, with 67% giving five stars and 13% giving one star (checked 10 November 2026). GoHenry says over 2.3 million children have used it since 2012.
Parents praise how easy it is for both them and their children, the controls and the money lessons. The complaints are mostly about the cost, especially the monthly fee and 50p top-ups on Everyday, transfer messages changing to pre-set options, and card payments being declined.
GoHenry vs HyperJar and other kids cards
| GoHenry | HyperJar | |
|---|---|---|
| Monthly fee | £3.99 to £5.99 per child, or £9.99 for up to four | None |
| Card cost | Standard card free; designs from £4.99 | £4.99 per card |
| Ages | 6 to 18 | Kids cards from 6; own account from 16 |
| Cash withdrawals | Yes, if the parent allows it | No |
| Interest | 2.63% AER on Plus and Max | None |
| Chores and money lessons | Yes | No chores; budgeting jars |
| Investing for your child | Junior ISA | No |
| Trustpilot | 4.0 | 4.7 |
When you look at options with no monthly fee, like HyperJar’s kids card, GoHenry’s £3.99 a month isn’t strictly necessary, but every business has running costs and GoHenry does more. Read my HyperJar review. GoHenry itself compares against NatWest Rooster Money and Monzo’s under-16s account, which are worth a look too. While other kids’ money apps have appeared, GoHenry was the true original. You can also hear from GoHenry on our podcast: teaching kids about money with Ashley Boonin.
Best Junior Stocks and Shares ISA
Investing for your child? Compare Junior ISA fees and fund choice side by side.
Compare Junior ISAsHow I tested GoHenry
I explored GoHenry’s features in the app and scored it with our six pillar method, which rates suitability for beginners, useful features, user experience, customer service, price and fees, and customer feedback. GoHenry scored 4.25 out of 5, highest for features, user experience and beginners, and lowest on price.
Every price, fee, age limit and protection detail on this page was re-checked on GoHenry’s website and its cardholder terms on 10 November 2026, along with the FSCS and gov.uk rules. If you sign up through our links we may earn a commission. That never changes the score.
Final verdict: is GoHenry worth it?
For parents who want a card with proper controls, automatic pocket money and genuine money lessons, yes, and it’s best value with three or four children on Max. If you mainly want a cheap way to give pocket money on a card, alternatives with no monthly fee do the basics.
What GoHenry offers is pretty amazing. The only real issue is the pricing: I’d like to see a free tier or no 50p top-up fees on Everyday. Over a year, one child on Everyday costs £47.88, and for many families that’s worth it for a child who spends safely and learns along the way.
FAQs
What age is GoHenry for?
Children aged 6 to 18. The parent must be 18 or over and live in the UK, and you can have up to four children on one parent account.
How much does GoHenry cost?
£3.99 a month per child on Everyday, £5.99 per child on Plus, or £9.99 a month for up to four children on Max. The first month is free.
Is GoHenry a bank?
No. The card account is e-money issued by IDT Financial Services, a Gibraltar-licensed bank, with GoHenry running the app. It isn’t a bank account and isn’t FSCS protected.
Is my child’s money safe with GoHenry?
Card money is held in a secure client account protected from IDT’s creditors, but not by the FSCS. Interest Savings are FSCS protected up to £120,000 and the Junior ISA up to £85,000 if a firm fails.
Can my child take cash out with GoHenry?
Yes, if you switch on cashpoint use. GoHenry doesn’t charge for withdrawals in the UK or abroad, though the cashpoint owner might, and you get a notification each time.
What can’t you buy with a GoHenry card?
The card is automatically blocked at 18+ businesses such as gambling, vape and tobacco shops and adult entertainment. The blocks depend on how shops register with Visa, so they aren’t perfect.
How do I cancel GoHenry?
In the app or by contacting member services. There’s a 14-day cooling-off period, no cancellation fee, and any money left is returned within about 7 to 10 working days.
What happens when my child turns 18?
They can use the card until its expiry date, then the GoHenry account closes. A GoHenry Junior ISA becomes theirs at 18.