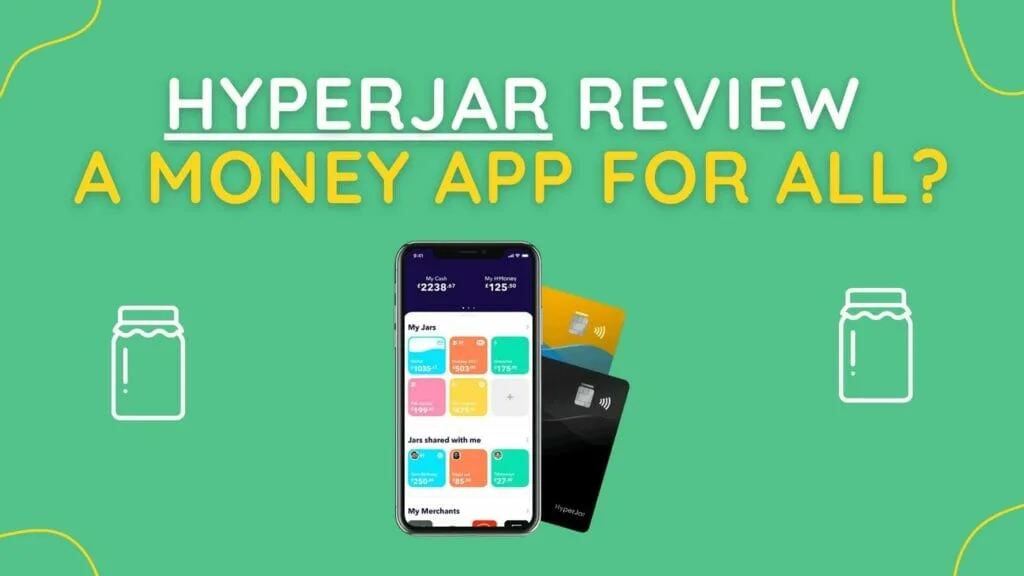
HyperJar is a free spending app and prepaid Mastercard that lets you split your money into digital jars, share jars with family and friends, and give kids aged 6 and over their own card. There’s no monthly fee: the main costs are £4.99 for a physical card and £1 if you go over the free top-up and transfer limits (checked 10 November 2026). The catch is that it isn’t a bank account: your money is e-money, so it isn’t FSCS protected, it pays no interest, and you can’t take cash out.
I rated HyperJar 4.08 out of 5 with our six pillar method. Its users rate it very highly, and it’s a genuinely useful family and kids option, but personally I’m not blown away: it doesn’t offer much other providers don’t, and locking money in with one shop to get a reward doesn’t sit well with me.
HyperJar review: my verdict at a glance
| HyperJar (checked 10 November 2026) | |
|---|---|
| My rating | 4.08 out of 5 |
| Best for | Envelope-style budgeting, shared family spending and a low-cost kids card |
| Monthly fee | None |
| Card cost | £4.99 for a physical card (adult or kids); adult virtual card free |
| Top-ups and transfers | 10 free loads a month (only one under £10) and 4 free transfers out; £1 each after that |
| Ages | Own account from 16; kids cards from 6, ordered by a parent or guardian |
| Protection | E-money, safeguarded but not FSCS protected; money committed to shops is held by that shop |
| Not available | Interest, cash withdrawals, cash deposits, overdrafts |
| Trustpilot | 4.7 out of 5 from 4,588 reviews |
- E-money: not FSCS protected and pays no interest
- Growth Rate money can only be spent with that brand
- £1 per load or transfer over the free monthly limits
- No cash withdrawals; physical cards cost £4.99
If you like the cash-in-envelopes way of budgeting, or want an easy way to give children pocket money on a card without a monthly fee, HyperJar does that well.
Who HyperJar suits (and who it doesn’t)
HyperJar suits you if
- You budget best by putting money into separate pots for food, bills or a holiday, and want a card that spends from the right pot.
- You want a kids card with no monthly fee and instant spending notifications.
- You share costs with a partner, housemates or a childminder and want a shared jar instead of a joint bank account.
- You travel and want a card with no added fees on foreign spending.
Look elsewhere if
- You want your money to earn interest or be FSCS protected.
- You or your kids need cash from a cashpoint (HyperJar cards can’t withdraw cash).
- You top up little and often, as small and frequent top-ups can trigger £1 fees.
- You want a full current account with direct debits, an overdraft or savings products.
How HyperJar works
You download the app, verify your ID and get a UK sort code and account number, so you or anyone else can pay money in. That money lands in your wallet, and you split it into jars: one for groceries, one for bills, one for a holiday, as many as you like. Some people call this cash stuffing or envelope budgeting; it’s the same idea as our sinking funds, but on your phone.
Your HyperJar Mastercard can be linked to any jar, so you spend from the right pot. You can also link a jar to specific shops, so a supermarket jar pays at the supermarket automatically, and you can freeze the card or block shops in the app. A virtual card is ready straight away and works with Apple Pay and Google Pay; a physical card usually arrives within 10 working days.
Shared jars
Any jar can be shared with other HyperJar users, who each need their own free account. The jar owner sets who can spend and how much, and everyone sees what’s been paid in and spent. That makes it handy for household shopping, a group holiday, or sharing kids’ costs with a childminder or co-parent. Remember that money in a shared jar belongs to the jar owner.
New to investing?
Get my free Checklist: the steps I would follow to open and fill an ISA without the classic mistakes. Plus one email a week, unsubscribe any time.
HyperJar kids and teens cards
Only a parent or legal guardian can order a kids card for a child under 16, from their own adult HyperJar account. It’s an extension of the adult account, so pocket money goes from your wallet into your child’s jar instantly and for free.
| Age | What they get |
|---|---|
| 6 to 12 | Physical kids card linked to a parent’s account; parents see every payment |
| 13 to 15 | Teen card that can also go on Apple Pay or Google Pay, plus their own version of the app on their phone |
| 16 and over | Can open their own HyperJar adult account with photo ID |
The controls a parent gets:
- Instant notifications every time your child spends.
- Freeze the card in seconds from your own app if it’s lost.
- Age blocks: kids cards won’t work in pubs, bars, nightclubs, off-licences, pawn shops or tobacconists, and HyperJar blocks gambling, crypto and adult content for everyone.
- Spending limits on any jar you share with your child.
There’s no monthly fee for kids cards, just the £4.99 card cost. Kids can’t contact customer support themselves, and like adult cards they can’t withdraw cash. For ideas on making money lessons stick, see how to teach kids about money.
HyperJar fees
The app is free to download and use. HyperJar’s fees, from its own fees page and help centre:
| What | Cost |
|---|---|
| Monthly or annual fee | None |
| Adult virtual card | Free |
| Physical card (adult or kids) | £4.99 one-off |
| Replacement card (lost or damaged) | £4.99 (free when your card expires) |
| Loading money from a bank | 10 free a month, only one of them under £10; then £1 each |
| Transferring money back to a bank | 4 free a month; then £1 each |
| Moving money between jars, kids and other HyperJar users | Free |
| Spending abroad | No added fees from HyperJar (Mastercard’s exchange rate) |
| Cash withdrawals | Not available |
Only one fee is charged per load, and loads of under £1 that break the limits have the whole amount taken as the fee. The easy way to stay free is fewer, bigger top-ups: £10 every two weeks instead of £5 every week. HyperJar’s terms also allow it to charge inactivity fees if an account isn’t used for 12 months.
HyperJar makes its money from the brands in its app, which pay it when you spend with them, plus these card and transfer fees.
 Read nexteToro vs Trading 212: Which Wins in 2026?
HyperJar Annual Growth Rate and cashback explained
HyperJar isn’t a bank, so it can’t pay interest. Instead it offers two kinds of reward for committing money to a particular shop in advance.
Annual Growth Rate (HyperVouchers)
You commit money to a partner brand in a jar, from as little as £1, and it grows by that brand’s Annual Growth Rate (AGR) for up to 12 months. HyperJar’s own example: £500 committed to TUI at a 10% AGR on 1 January becomes £550 to spend with TUI by 31 December. Rates vary by brand and are shown in the app.
The catch: the money, and the growth, can only be spent with that brand. There’s no time limit to spend it and you can gift it to another HyperJar user, but you can’t move it back to your bank. When we asked HyperJar about this, they told us they only really offer refunds in an emergency. Having my money locked in to get the AGR doesn’t sit well with me, as someone who likes full control of my money at all times. If you were going to spend with that shop anyway, it can be a nice extra.
Cashback Vouchers
These work like digital gift cards. Buy one for a brand and you get cashback straight away, usually at a higher rate if the cashback stays with that brand and a lower rate if you want it to spend anywhere. HyperJar’s own example is a £100 H&M voucher giving £7.50 to spend with H&M or £5.50 to spend anywhere. Once you buy a voucher, the money is held by that shop, not HyperJar. For other ways to earn money back, see our best cashback apps.
Is HyperJar safe?
Yes, in the sense that it’s properly regulated and uses strong security, but it’s important to understand what isn’t covered.
- Not a bank, not FSCS protected. Money in your HyperJar account is e-money issued by Modulr FS Limited (FCA number 900573). HyperJar’s company, Hyperlayer Limited, is Modulr’s registered agent (FCA number 902842). The card is issued by Monavate Limited (FCA number 901097).
- Safeguarded instead. Your e-money is kept in segregated accounts separate from the company’s own money, which is the same system used by apps like PayPal and Wise. If Modulr went bust, that money should come back to customers, but it may be at risk and there’s no FSCS payout.
- Money committed to shops is different. HyperVouchers and Cashback Vouchers are advance payments held by the brand, so they depend on that brand.
- App and card security: passcode, face or fingerprint login, instant notifications, 3D Secure checks on online payments, and freezing the card in the app. HyperJar says it uses 256-bit encryption.
With no FSCS cover and no interest, HyperJar works best as a spending and budgeting account rather than a place to keep savings. You can check any provider with the FSCS protection checker.
How to open a HyperJar account
- Download the free app from the App Store or Google Play (you need to be 16 or over and live in the UK).
- Sign up with your details and photo ID; HyperJar says there’s no impact on your credit score.
- Get your virtual card straight away, or order a physical card for £4.99.
- Pay money in from your bank using your new sort code and account number (cash and cheques aren’t accepted).
- Create jars, link them to shops and your card, and add kids cards from the Profile tab.
Not sure where to start?
Pick your goal (debt free, start investing, side income, saving for something big) and get a free money plan you can level up on. Takes about two minutes.
Get your free money planHyperJar reviews: what customers say
On Trustpilot, HyperJar scores 4.7 out of 5 from 4,588 reviews, with 86% giving five stars and 5% giving one star, and 1,613 reviews in the past year (checked 10 November 2026). It replies to all negative reviews.
Reviewers love how easy the app is, the fast live chat support and how simple it makes pocket money and family spending. The complaints are mostly about payments being delayed, accounts being restricted during ID checks, and people expecting to get cash out at a cashpoint, which the card doesn’t allow.
HyperJar vs GoHenry
HyperJar’s kids card is a cheaper alternative to GoHenry, which charges a monthly fee but adds cash withdrawals, savings interest on its higher plans and chore payments. How they compare (each provider’s own pages, checked 10 November 2026):
| HyperJar | GoHenry | |
|---|---|---|
| Monthly fee | None | £3.99 per child (Everyday), £5.99 per child (Plus), £9.99 for up to four (Max) |
| Card cost | £4.99 per physical card | Standard card free; personalised designs from £4.99 |
| Ages | Kids cards from 6; own account from 16 | 6 to 18, parent account 18+ |
| Top-ups | 10 free a month (one under £10), then £1 | Everyday: 1 free a month then 50p; Plus and Max free |
| Cash withdrawals | No | Yes, if the parent allows it |
| Interest on savings | No | 2.63% AER on Plus and Max |
| Protection | E-money, safeguarded, not FSCS | E-money in a protected client account, not FSCS (interest savings held at a bank, FSCS) |
| Trustpilot | 4.7 | 4.0 |
Introducing kids to payments in a controlled way is a fantastic idea, and we back every company that brings money skills into children’s lives early. The kids side of HyperJar is very similar to another brand we like, GoHenry. Read my full GoHenry review, or for budgeting apps for adults, my Snoop review.
Best Budgeting Apps UK
HyperJar, Snoop, Emma and more budgeting apps compared side by side.
Compare budgeting appsHow I tested HyperJar
I scored HyperJar with our six pillar method, which rates suitability for beginners, useful features, user experience, customer service, price and fees, and customer feedback. HyperJar scored 4.08 out of 5.
Every fee, age limit and feature on this page was re-checked on HyperJar’s website, help centre and terms on 10 November 2026, along with the FSCS rules.
Final verdict: is HyperJar any good?
For families who want a no-monthly-fee kids card, and for anyone who budgets best with separate pots of money, yes. The app is genuinely easy, sharing jars works well and its users love it. Just keep top-ups to £10 or more, and remember it isn’t a savings account: no interest and no FSCS cover.
Where it falls short for me: the jars idea isn’t unique any more, and the best rewards need you to lock money in with a single shop. I like what the company stands for and it’s definitely one to watch, but I’d like to see more new products.
FAQs
Is HyperJar a bank?
No. HyperJar is a spending app and prepaid card. Your money is e-money issued by Modulr FS Limited, an FCA-authorised e-money institution, and the card is issued by Monavate.
Is my money safe with HyperJar?
It’s safeguarded in segregated accounts but isn’t covered by the FSCS. Money you commit to a shop through HyperVouchers or Cashback Vouchers is held by that shop.
Is HyperJar free?
There’s no monthly fee. A physical card costs £4.99 (adult virtual cards are free), and you pay £1 per load or transfer over the free limits: 10 loads a month (only one under £10) and 4 transfers out.
What age is HyperJar for?
You can open your own account from 16. Parents and guardians can add kids cards for children from age 6, and 13 to 15 year olds can add their card to Apple Pay or Google Pay.
Can you withdraw cash with HyperJar?
No. HyperJar cards can’t be used at cashpoints, for cashback at tills or at a bureau de change, in the UK or abroad.
Can I use HyperJar abroad?
Yes, anywhere that takes Mastercard, and HyperJar doesn’t add fees on foreign currency spending. Turn on Spend Abroad in the app first.
Does HyperJar pay interest?
No. Instead, some brands pay an Annual Growth Rate on money you commit to spend with them, for up to 12 months, but that money can only be spent with that brand.